




 IT Managed & Outsourcing
 Leader in AI-First Product Engineering Read Full Article
 Contact Us
Lending only works when origination, underwriting, servicing, collections, and compliance data move as one system. These are the core capabilities we've already engineered into lending platforms.
Core Capabilities Behind Our Lending Software Development Services




Our Engineering Strength in Numbers
FinTech Products Delivered
Fraud Detection Accuracy
Security SLA for Transactions
Cost Reduction in Operations
Lending Workflows Digitized
Client Retention on Lending Projects

Built for lenders losing applicants to slow approval cycles. Our loan lending app development pulls bureau data, verifies documents, and applies AI credit scoring to move applications through underwriting without the back-and-forth that stalls approvals today.

Built for lenders tracking active loans across disconnected spreadsheets and legacy tools. Through custom loan management software development, we centralize account status, repayment schedules, and portfolio health into one system your team can actually trust.

Built for mortgage lenders running underwriting and disclosures through manual checkpoints. We've delivered mortgage loan origination systems that move applications from intake through closing with fewer handoffs and less document chasing.

Built for mortgage teams losing leads between first contact and closing. We've built mortgage CRM platforms that track every lead by pipeline stage, so follow-up never depends on someone remembering to do it.

Built for mortgage operations still running rate locks, appraisal orders, and underwriting reviews by hand. We've layered mortgage automation into origination workflows using AI in mortgage lending to cut the manual steps that slow closings down.

Built for lenders where every application still needs a human to move it from one stage to the next. We've built loan processing automation that routes applications, triggers verifications, and flags exceptions without manual intervention.

Built for lenders whose borrowers expect a mobile-first experience and don't get one. As a lending app software development company, we've built money lending apps that handle applications, approval tracking, and repayment inside a single borrower-facing app.

Built for lenders where post-disbursement operations eat more time than origination itself. Our loan software development automates payment processing through payment software, escrow handling, and account updates after the loan is funded.

Built for lenders where overdue accounts pile up faster than teams can follow up. We've built automated debt collection workflows that trigger reminders, escalate delinquent accounts, and log every borrower interaction as part of our software development approach.

Built for platforms connecting individual lenders and borrowers outside traditional banking rails. Our p2p lending software development handles borrower-lender matching, risk scoring, and fund disbursement with full transaction traceability.

Built for lenders pricing risk manually and losing margin to inconsistent rate decisions. We've built loan pricing software by lending analytics that adjusts rates based on real-time risk models, so pricing stays consistent across every loan type.

Built for lenders carrying exposure they can't fully see in real time. Through custom loan management software development, we build solutions that track asset value, exposure thresholds, and portfolio-level risk as loan books shift.
Ready for Lending Software That Actually Works Like Your Business Does?
We've engineered custom lending software development for origination, underwriting, and collections before. Let's build yours next.

Before writing a line of code, we've sat with lending teams to map where approvals stall, where risk visibility breaks down, and where compliance checks eat up time they don't have. Our lending software consulting turns that audit into a technology roadmap that fixes the actual bottleneck, not just the symptom.
We've built custom lending software around how lenders actually operate, not a generic template. From origination and underwriting to servicing and collections, every workflow is engineered for your loan products, your risk models, and your compliance requirements.
Legacy loan management systems slow lenders down long before anyone notices the cost. We've modernized aging platforms into scalable, API-ready architecture, improving processing speed, reporting accuracy, and security without disrupting active loan books.
Lending rarely runs on one system. We've connected loan origination platforms, core banking systems, credit bureaus, CRMs, and payment gateways so data moves in real time instead of getting stuck in manual handoffs between teams.

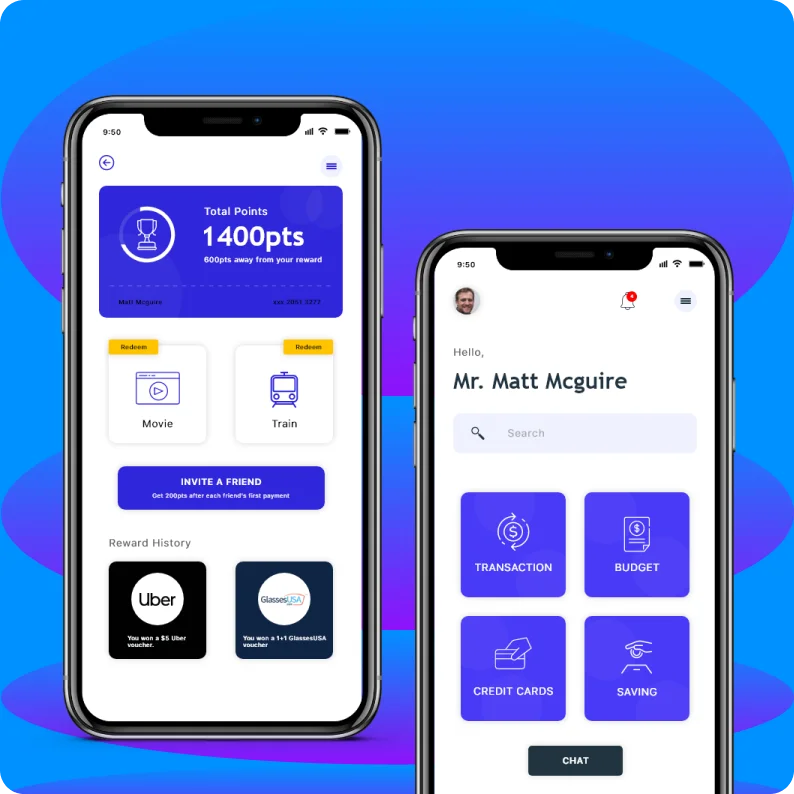
Budget management had stayed a manual, paper-based habit for millennials who found traditional finance tools boring and disengaging. The client needed a way to make expense tracking feel automatic, not like a chore.

We built a chatbot-centric budget management app on Google Dialogflow, engineered to pull financial data securely and respond to users in an interactive, personality-driven way instead of static forms and dashboards.

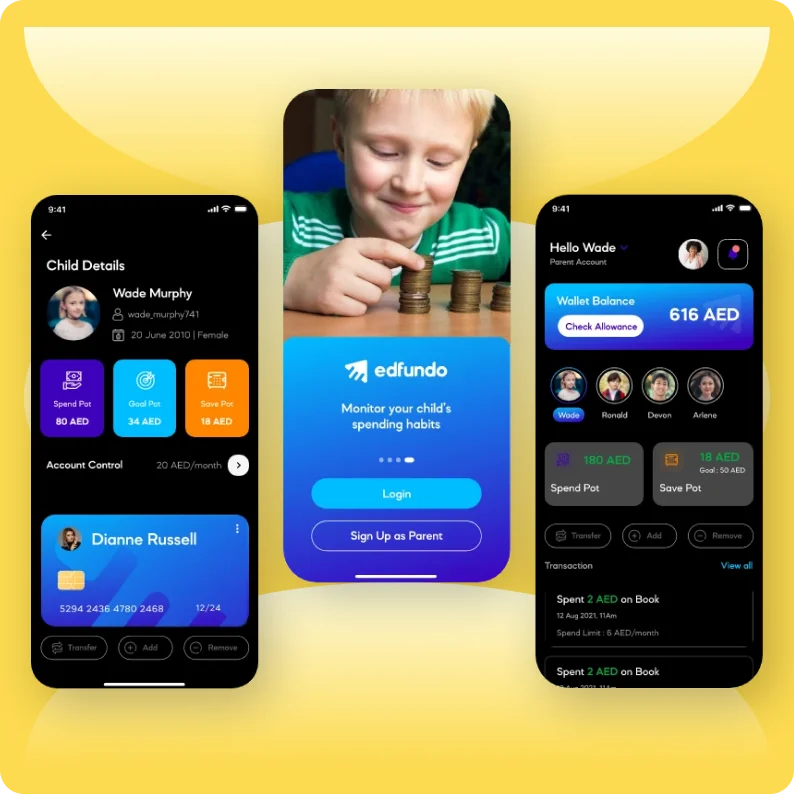
Financial literacy among children and teens stayed low, and the client, a team of former educators, needed a technology partner to turn that gap into a working financial product for kids, parents, and educators.
We built Edfundo's financial intelligence platform end to end, including a digital learning lab, a prepaid debit card experience, and parental controls, backed by a scalable Node.js infrastructure across native iOS and Android apps.
A fractional real estate investment platform needed more than a clean user interface. It needed a secure, compliant financial engine to manage multi-wallet transactions and automate dividend distribution at scale.
We engineered a complete financial backend, including an admin panel to manage the entire ecosystem, automated dividend calculation and distribution logic, and a multi-wallet system built on Node.js and MongoDB for reliability under financial-grade load.
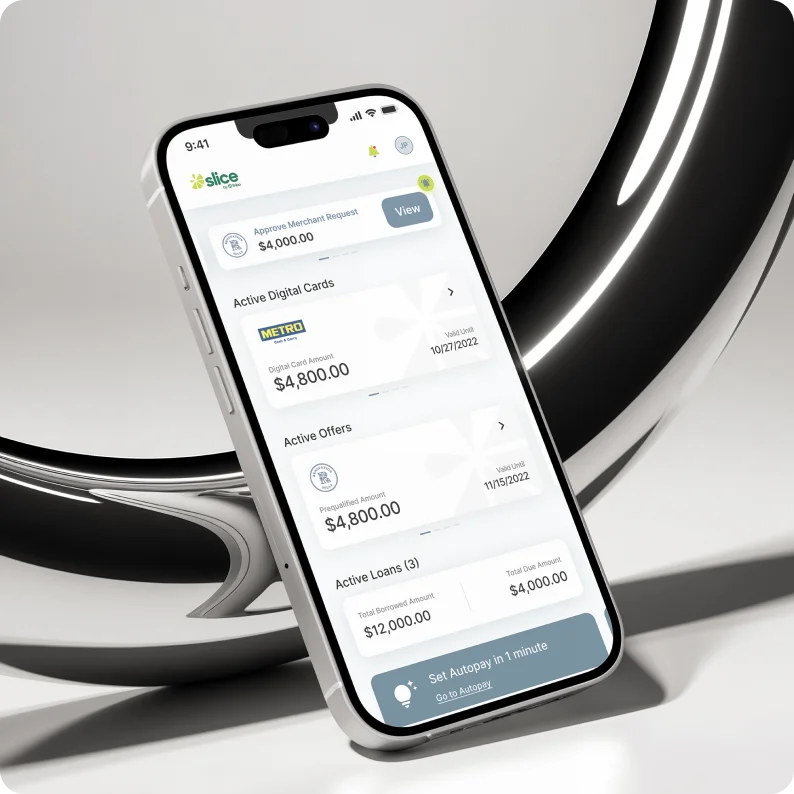









Origination, underwriting, servicing, and collections all depend on each other. We’ve designed lending platforms around those handoffs before, so your team isn’t stuck working around the software during a loan’s busiest stages.
As a lending software development company, Appinventiv brings the delivery strength of 3000+ digital solutions across various technology and industries with a team of 1700+ technology specialists. That depth has already gone into lending platforms handling real borrower data, real risk models, and real compliance pressure.
Audit trails, disclosure workflows, and data controls need to exist from day one. We’ve structured lending systems this way before, so compliance teams aren’t left fixing gaps after launch.
Most lenders run on a mix of credit bureaus, core banking systems, CRMs, and payment gateways. We’ve connected these systems for lending platforms before, without creating fragile shortcuts that break under load.
We’ve applied AI to real lending problems before, credit scoring, fraud detection, collections prioritization, not features added for the sake of a pitch deck.
Launch isn’t the finish line for a lending platform. We’ve supported systems through monitoring, updates, and scaling long after go-live, because loan books grow and regulations change.
The Right Lending Software Development
Partner Makes the Difference
We’ve been the team behind lending platforms that scale, stay compliant, and actually get used. Let’s see what that looks like for you.

The India's Fastest-Growing Companies 2026 Recognised by TIME and Statista

Statista High Growth Companies APAC - 2026
Statista India's Growth Champions 2023


We've applied AI to underwriting, fraud detection, and credit scoring before, helping lenders catch risk signals and approve creditworthy borrowers faster, without relying on static rules alone.
We've built predictive analytics models that read repayment history, borrower behavior, and portfolio trends, helping lending teams spot default risk earlier and act before it becomes a write-off.
We've used generative AI development to handle routine borrower queries, loan status updates, and application guidance, keeping support teams focused on the cases that actually need a human.
We provide cloud consulting to move lending platforms onto cloud-native architecture before, giving lenders room to scale, release faster, and stay resilient during high-volume application periods.
We provide blockchain consulting to make loan agreements and P2P lending transactions tamper-proof and auditable, reducing fraud risk and strengthening borrower and investor trust.
We offer RPA development to automated repetitive loan processing steps before, document verification, data entry, status updates, cutting manual work without cutting corners on accuracy.


Good Tech Choices Come
From Having Built With Them Before
We've made these exact stack decisions on real lending platforms, not just in theory. Let's talk about what fits yours.
We start by understanding how origination, underwriting, servicing, and collections actually run today, where approvals stall, where risk visibility breaks down, and where compliance checks eat up time your team doesn't have.
Every lending platform we've built has been architected around uptime, secure data handling, user roles, and compliance needs from the start, not added in after the fact. The result is a delivery plan your product and risk teams can actually work with.
Loan officers, underwriters, borrowers, and collections teams all need different things from the same system. We design role-specific workflows so each user gets a fast, clear path through their part of the process.
Build and integration move together, since lending platforms rarely run alone. Credit bureaus, core banking systems, CRMs, and payment gateways get connected as we build, not bolted on afterward.
Before release, we test for performance, data accuracy, access control, audit trail integrity, and workflow stability, catching issues before live borrowers or auditors do.
Rollout happens in controlled phases, backed by monitoring and performance checks. As loan volumes grow and regulations shift, we've kept these platforms improving well past launch.
We've used AI internally across code generation, testing, and QA cycles to cut development time on lending platforms, without cutting corners on accuracy or compliance review. It's part of how we move faster on complex builds, not a replacement for engineering judgment.
As a lending app software development company, we build loan origination platforms, loan management software, mortgage software, mortgage CRM systems, loan servicing platforms, automated debt collection tools, P2P lending software, loan pricing engines, and collateral management systems, along with consulting, modernization, and integration services across the full lending lifecycle.
Yes. We've built custom lending software for credit unions, microlenders, mortgage brokers, commercial banks, leasing companies, and payday lenders before, and every platform is engineered around the client's loan products, risk models, and compliance requirements.
Through custom lending management software development, we build loan origination software, loan servicing platforms, mortgage automation systems, P2P lending software, loan pricing engines, and limit and collateral management systems, each designed for a specific stage of the lending lifecycle.
Yes. We've modernized aging loan management platforms into scalable, API-ready architecture before, improving processing speed, reporting accuracy, and security without disrupting active loan books.
We build lending platforms with audit trails, disclosure workflows, and access controls in place from the start. Our teams have worked with compliance standards including PCI DSS, GDPR, AMLD, PSD2, and fair lending regulations.
Yes. We've integrated lending platforms with core banking systems, credit bureaus, CRMs, and payment gateways before, so data moves in real time instead of getting stuck in manual handoffs.
Yes. We've applied AI to credit scoring, fraud detection, and collections prioritization for lending clients before, and we also use AI internally across our own development and QA process to speed up delivery without compromising accuracy.
Lending software development cost typically ranges from $40,000 to $400,000 or more, depending on feature complexity, integrations, compliance requirements, and the platform's scale. Connect with our lending software developers for an accurate estimate.
A basic lending platform can take 3 to 4 months to build. A complex platform with multiple integrations and advanced features can take a year or more, depending on scope.
To move quickly, we typically need detailed project requirements, access to relevant data and systems, regular feedback during development, and involvement at key project milestones.