





How AI in Payments Affects the Digital Payments Industry
 Share -


- 01The state of AI in the Payments industry in 2026
- 02Evolution of AI: The Catalyst for a Smarter Payment Ecosystem
- 03AI Tools and Techs For the Payment Industry
- 04AI Use Cases in Payments: 5 Applications of AI in Payments
- 05How to Integrate AI into Your Existing Payment System
- 06Challenges of AI in the Payments Industry & Their Solutions
- 07ROI of AI in Payments
- 08How Appinventiv is Supporting AI in Payments
Key takeaways:
- Running a payment app or website without AI is risky, as it helps predict rushes, detect fraudulent behavior, and enhance customer satisfaction.
- The global AI in finance and payment market is projected to grow from $38.36 billion in 2024 to $90.33 billion in 2030, with a CAGR of 30.6%.
- AI empowers businesses with improved operations, fraud prevention, and better customer interaction, while offering consumers easier, safer, and more personalized payment experiences.
- AI excels at identifying unusual patterns and suspicious activities, significantly improving fraud prevention and overall payment security.
- AI-powered tools like chatbots and personalized payment suggestions streamline the payment process, making it more seamless and tailored to individual preferences.
Did you know there is a costly connection between your payment services and your business revenue? Yes! According to Fintech Times, 45% of consumers won’t retry a payment following a false decline – and 42% are reluctant to return to an app or website after such an experience.
Thus, running your payment app or website without AI is like teetering your business on the edge of chaos, battling pain points that leave you in the dust, trying to figure out what hit you, and ultimately threatening your survival in the market.
A smart AI payment system is adept at predicting the rush, catching fishy behavior as it happens, and dishing out deals that make folks happy to hit pay. Fast-forward to 2026 in the payments realm—AI is no longer just a helpful gadget—it’s what separates the hotshots from the no-shots.
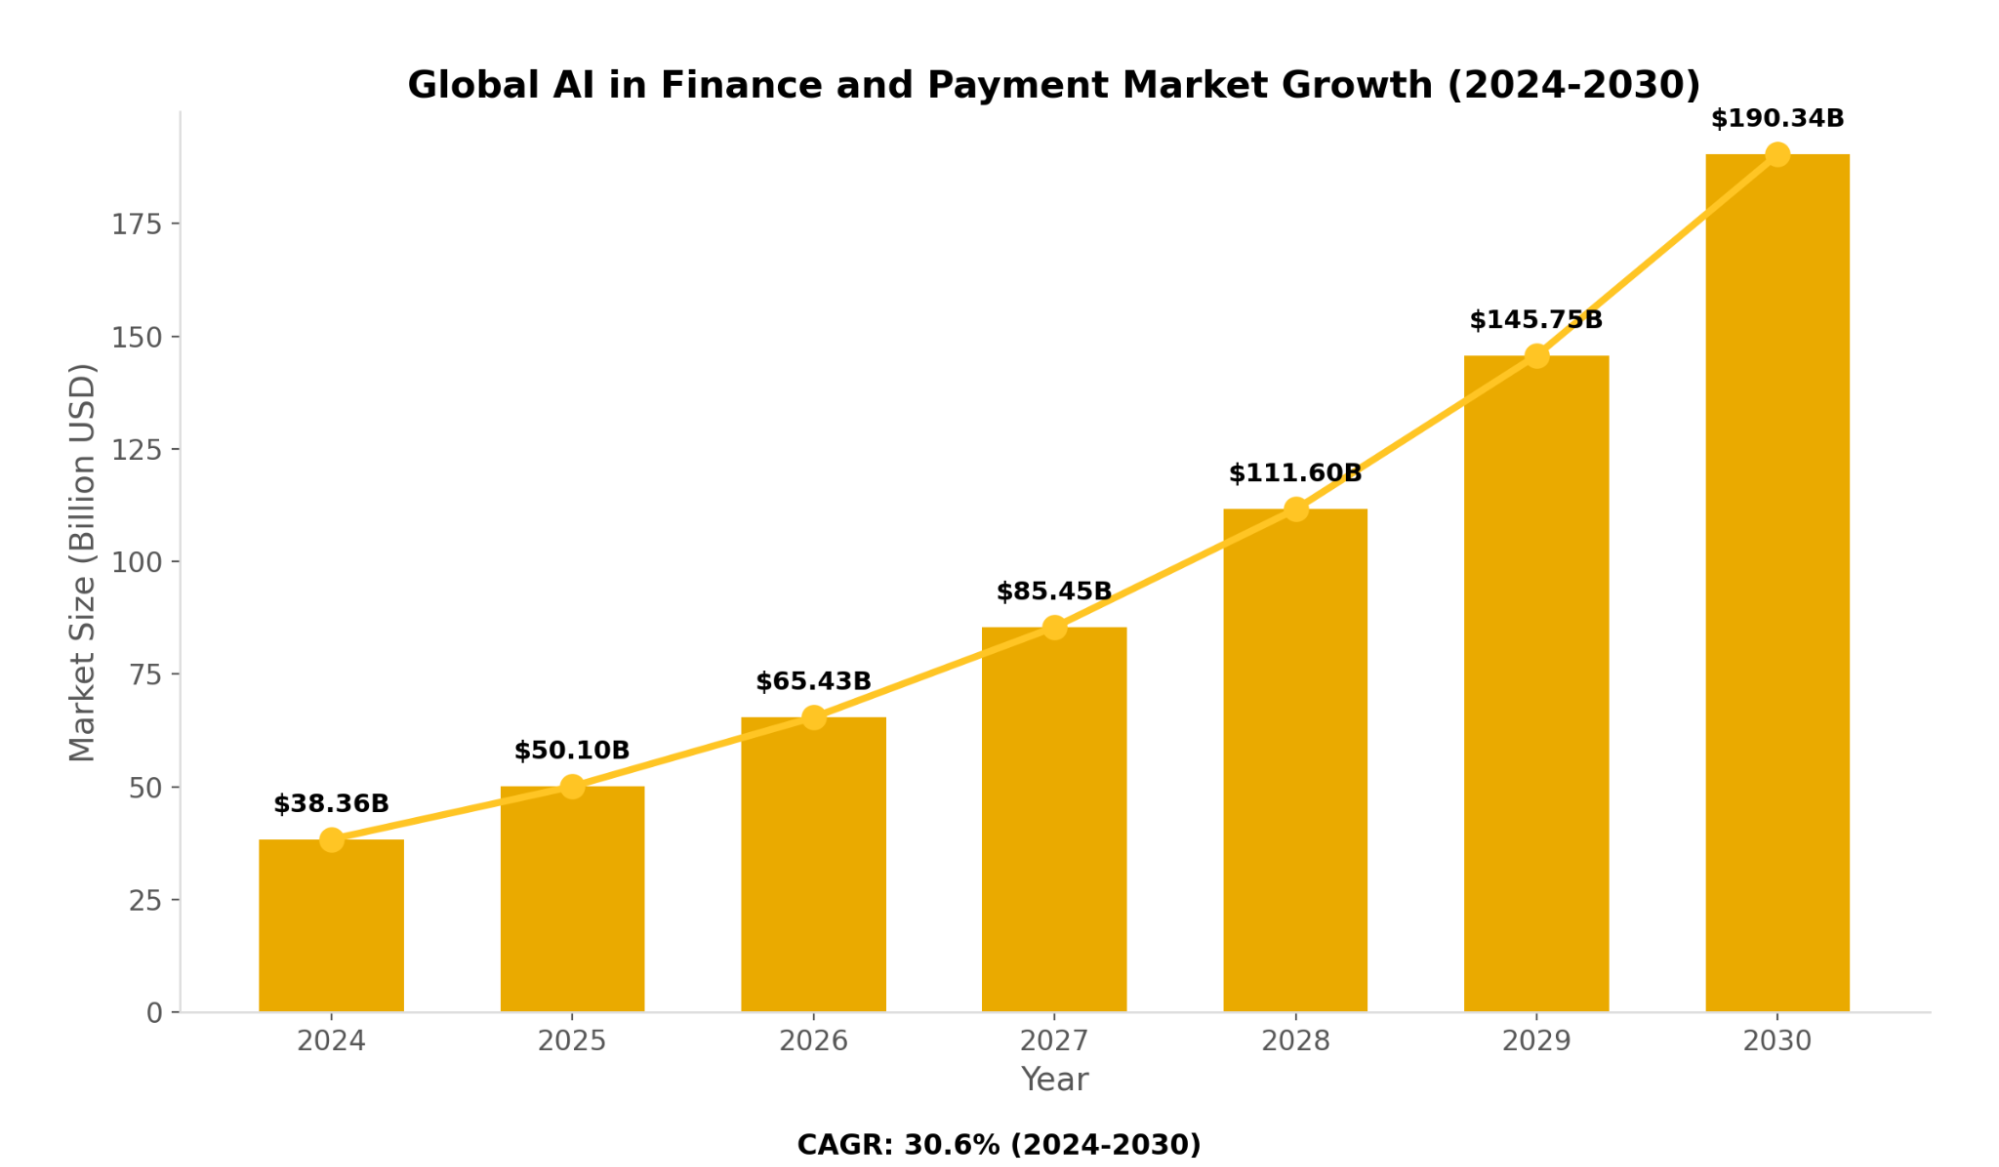
The global AI in finance and payment market was estimated at USD 38.36 billion in 2024 and is expected to reach USD 190.33 billion in 2030, with a compound annual growth rate (CAGR) of 30.6% from 2024 to 2030 (Source: Markets and Markets).
The state of AI in the Payments industry in 2026
By 2026, AI will become a key part of paying for things, changing how we make, process, and protect transactions. This change affects two main areas: how customers pay and how businesses handle payments.
- For businesses
AI gives them tools to improve their work, fight fraud, and connect with customers better. This helps them work more and make more money in a tough market.
- For customers
AI makes paying easier, safer, and more personal. It meets the growing need for smooth and customized money experiences.
These improvements show a big change. AI doesn’t just make payments faster – it changes how customers and businesses interact with each other and with the technology that links them.
This part looks at these two viewpoints, shedding light on the new ideas, hurdles, and future promises of AI in the payments industry as it keeps changing.
| Aspects | The Merchant Side | The Consumer Side |
|---|---|---|
| Use Case | AI impacts streamlining how transactions are processed, spotting fraud, and interacting with customers. | AI boosts ease with custom-made payment options, shields against cons, and smooths everything. |
| Personalization | AI uses what it knows about shoppers to sling deals on prices that change special offers made just for you. | AI digs into what you’ve bought before and the stuff you dig to suggest ways to pay, like ‘buy now, pay later’ or e-wallets. |
| Fraud Prevention | Those brainy AI computer thingies pick up on the bad guys’ tricks in your spending so your cash is kept safe. | AI helps you spot the shady stuff quickly by flagging anything fishy. It cuts down on scams and the hassles of returns. |
| Emerging Innovations | AI’s doing the grunt work, like sorting out where your payments go so things run smoother at the office. | Your techy wallet has some AI smarts—it tells you the best time to pay and what money to use when shopping from another country. |
| Impact on Experience | Store owners notice more sales going through and fewer bucks lost, which cranks up the profits and keeps customers returning. | Shoppers dig the smooth payments and tougher security, ramps up trust in online buys. |
Therefore, Artificial intelligence in Payments brings awesome new levels of quickness and safety, making things way more personal for everyone. Think about how we’re using digital wallets and cryptocurrencies; AI’s the big brain behind all the cool changes happening in the payment world. This post will dive into the journey of AI in the payments industry, the gear that’s making all this magic happen, the real-deal uses we’re seeing, and tips for companies looking to tap into this power.
Assess your existing infrastructure, identify high-value AI use cases, and develop an implementation strategy aligned with your business goals.
Evolution of AI: The Catalyst for a Smarter Payment Ecosystem
Artificial intelligence in payments stands ready to tackle these obstacles, turning the payment field into a domain that’s slicker, safer, and easier for folks to use. Check out how:
1. Scalability for Global Adoption
AI examines how transactions flow, foresees busy times, and tweaks the process chain to make systems expand. Machine learning in banking & finance adjusts what resources go where on the fly, dodging slowdowns and letting platforms manage loads of transactions with no problem.
2. Interoperability: Connecting Different Systems
Systems need to work together – that’s what interoperability means. It’s super important for a payment system that makes sense together. If we don’t have it, people dealing with payments get all mixed up, and companies must deal with mismatched systems.
If you’re a shop owner trying to take CBDCs, good luck fitting that square peg into the round hole of your old credit card or PayPal setup at the cash register. This will ensure money can slide through different countries and tech without a hitch.
3. Processing Stuff Right Away
AI speeds up the check and completion of transactions with its knack for handling huge data sets. Neural networks can spot weird stuff or scams and say yes to good payments in a flash. At the same time, they call out iffy things to look at.
4. Better Protection
AI-powered payment systems are top-notch at catching patterns that might slip by us. It monitors money moves for anything odd, like spending that suddenly skyrockets or logging in from a strange place. This helps stop scammers in their tracks. Also, stacking up top-end code scrambling with AI’s ability to sniff out dangers gives us a strong shield against online baddies.
5. Taking User Experience Up a Notch
AI-powered Chatbots take the hassle out of settling payment quarrels and tailor the way you pay, making things feel seamless and natural. It’s got a knack for guessing what you might not, nudging you towards Apple Pay for a speedy tap or a crypto wallet when you don’t want to get hit with fees. Plus, it’s all about cutting down on the bumps along the way.
AI Tools and Techs For the Payment Industry
The internet payment biz has changed with artificial intelligence in payments, joining forces with related tech. These gadgets make things safer, better the user experience, keep stuff running smoothly, and stick to the rules. Here’s a look at the usual AI stuff making waves in this field.
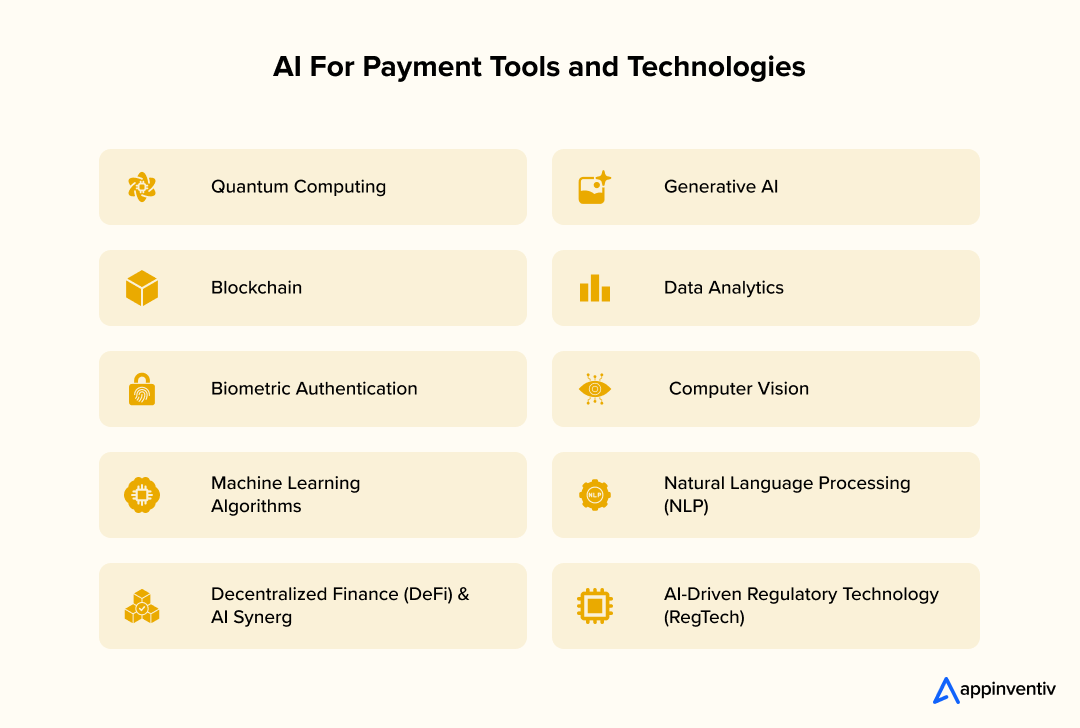
Machine Learning Algorithms
Machine Learning Algorithms—part of AI—let payment setups get smart on their own from tons of info without anyone telling them what to do. They’re a big deal in the online payment world, and here’s how:
- Fraud Detection: Machine learning tools sift through transactions, catching weird patterns that might scream scam. They pick up on where you are, the gadget you’re using, and what you buy to determine if something’s fishy. Then, they slap a risk number on it and wave a red flag at any dodgy dealings that need a closer look. This neat trick cuts down on mistakes and keeps things safer.
- Customer Segmentation: These smart programs group folks by what they buy, what they like, and who they are. That way, shops and card swipers can whip up custom deals, slash prices just for you, and make ads that might work.
- Predictive Analytics: These clever systems give businesses the heads up by playing the fortune teller on things like who’s gonna bail on the service, who might miss their payments, or when folks will splash the cash. This helps them handle their dough better, stock up just right, and have enough people around when it gets busy.
Natural Language Processing (NLP)
NLP applications for modern enterprises allow computers to grasp and reply to what we say, causing a revolution in how customers interact within the money-moving world:
- Voice-Based Transactions (Talking to Pay): Thanks to NLP, people like Alexa and Siri can handle cash exchanges by listening to what we tell them. It’s like you can take care of bills with just your voice, which is super easy and hands-off.
- Chatbots (Automated Answer Givers): These smart chatbots are always available to solve common questions about cash movements, money-back deals, or how much dough you’ve got in your account, all while cutting down on costs and getting back to folks faster by dealing with the easy stuff on their own.
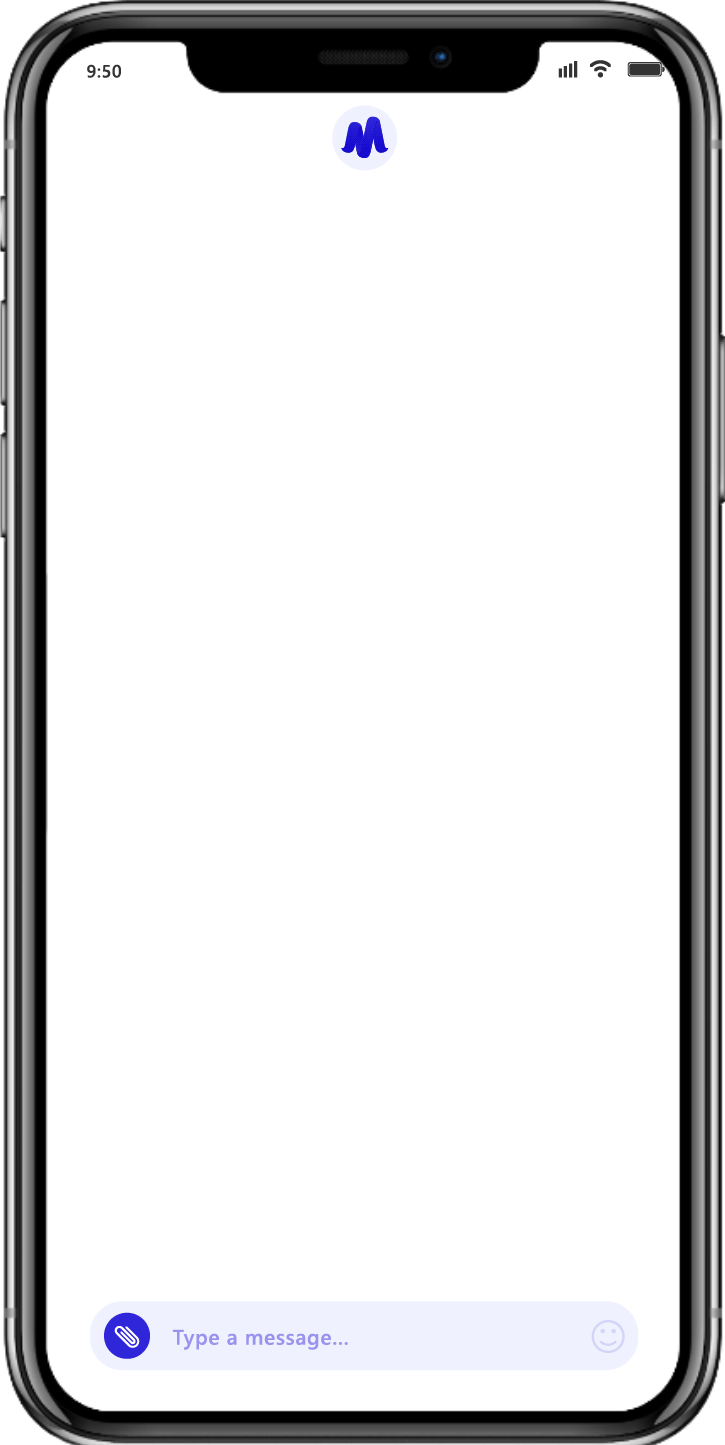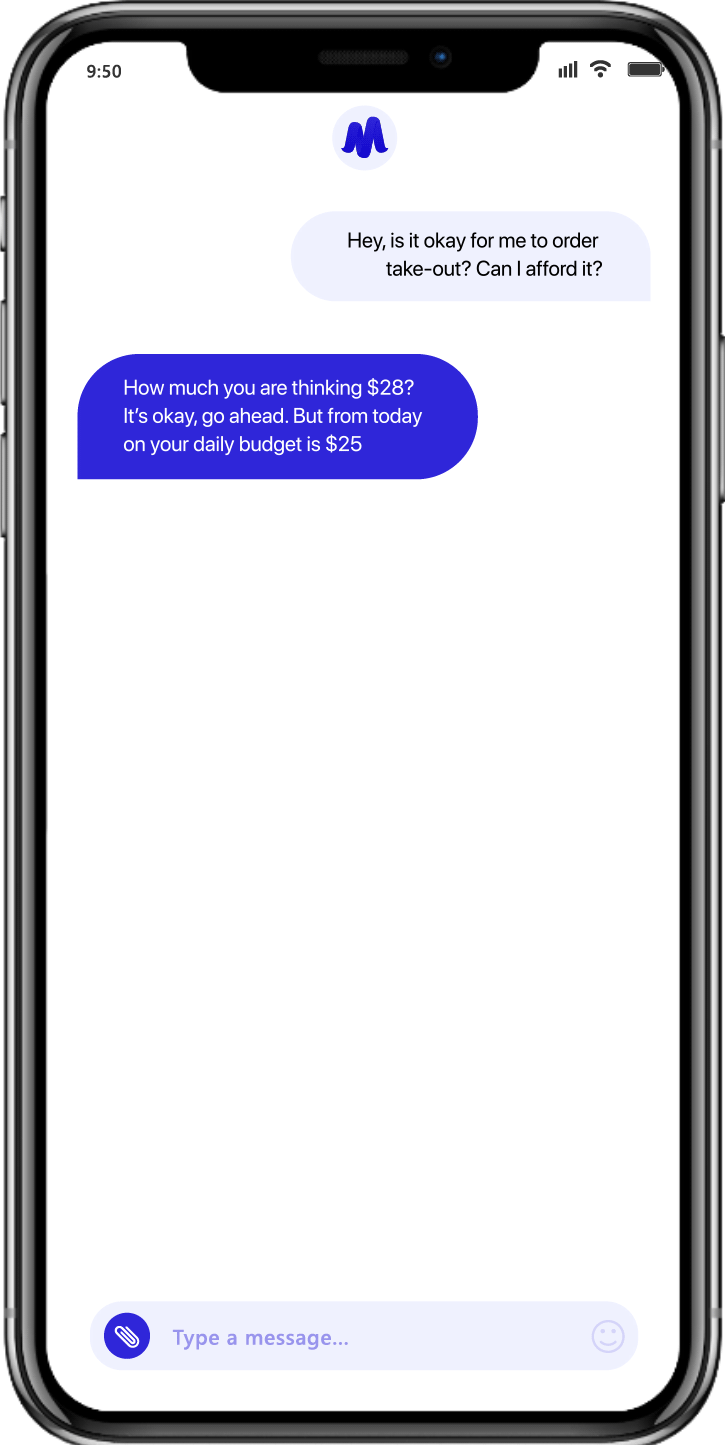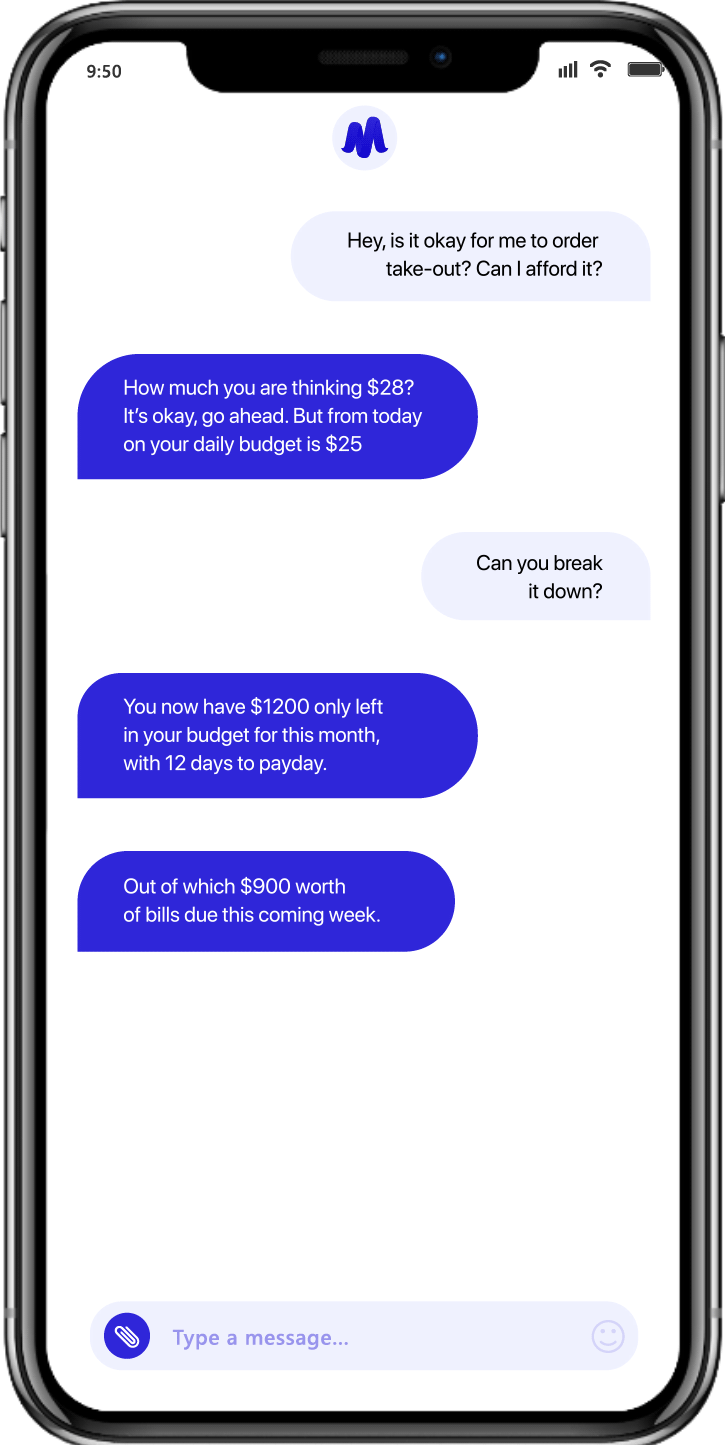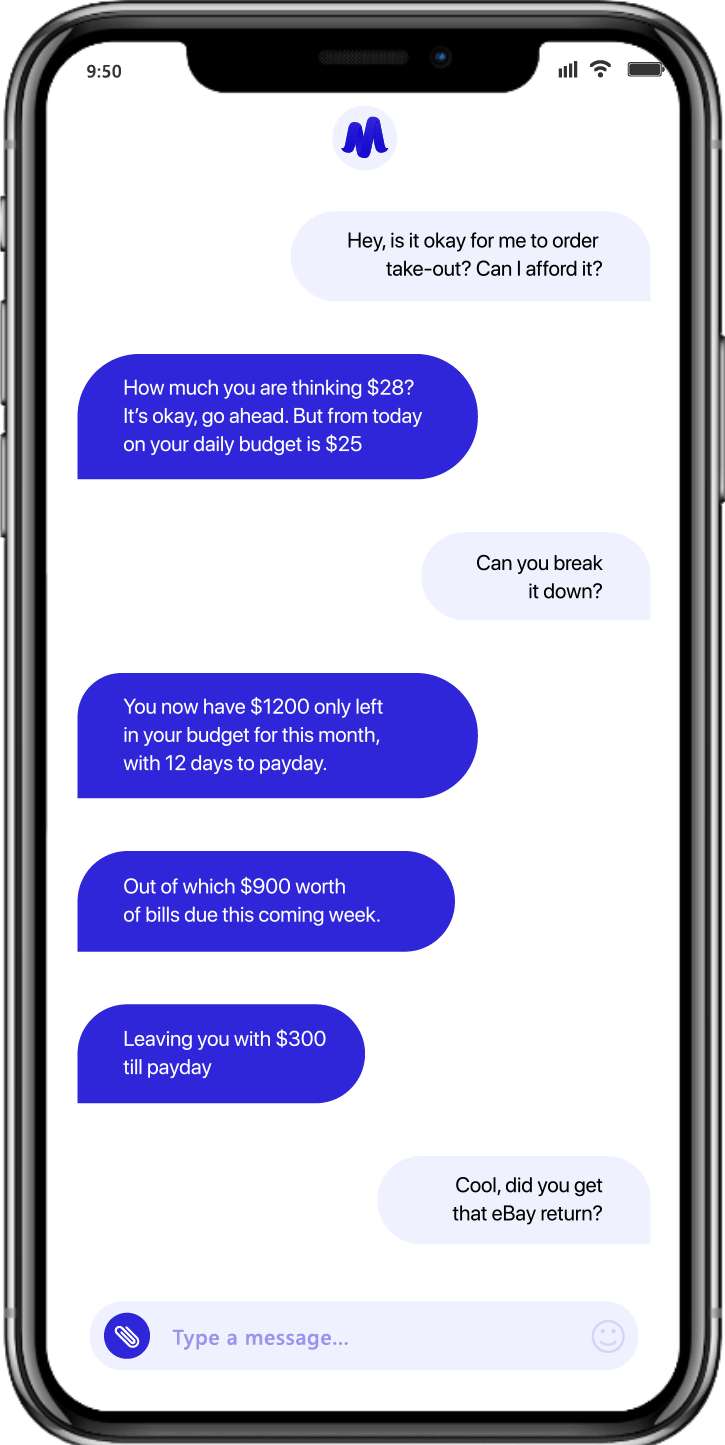
AI-Powered Chatbot App: Mudra Budget Management App Appinventiv’s AI experts have engineered an AI-powered Chatbot App – Mudra budget management solution. See how AI integration and automation align with advanced financial and banking principles by delivering personalized, efficient, and engaging user experiences:
Results Mudra: The Budget Management App turns budget management into a dynamic, user-focused experience. Its success, spanning 12+ countries, reflects this AI-aligned strategy, where technology solves practical problems while forging a trust-based bond with users. |
- Sentiment Analysis: NLP programs can tell how happy customers are by sifting through what people say in reviews, on social media, or during help chats. Companies use this info to fix what bugs people and make paying smoother.
Generative AI in Payments
Generative AI in finance is known for forming new stuff or solutions from patterns it learns and is getting pretty popular in the money-moving world:
- Content Creation: Generative AI in payments whips up personal marketing stuff, think emails or ads, to boost payment services or special deals to keep customers returning.
- Personalization: Putting together payment plans that fit you to a generative AI cranks up how much customers want to stick around.
- Enhanced Interaction: Generative AI in payments lets you have smoother talks about things like changing FAQs or fun payment step-by-step, making using it easier and making people like it more.
Blockchain
Now, blockchain in fintech, often seen hanging out with AI, sets up a tight and open-as-a-book base for systems that handle your cash:
- Secure Authentication: Blockchain’s no-nonsense way of checking who’s who and what’s what makes it tough for hackers to mess with the data or swipe information.
- Smart Contracts: These nifty contracts just do their thing handling cash exchanges, like when money gets shelled out after someone gets their package – it cuts out the wait and the extra people in the middle.
Decentralized Finance (DeFi) and AI Synergy
AI’s giving Decentralized Finance (DeFi) a big boost, what with making money work smarter, keeping an eye on the risky stuff, and playing by the rules:
- AI-Driven Yield Optimization: Algorithms predict the best investment strategies within DeFi protocols, maximizing user returns.
- Real-Time Risk Analysis in DeFi Transactions: It’s watching for wacky market swings and iffy smart contract spots so everyone’s money doesn’t go poof.
- Governance and Compliance in Decentralized Systems: AI secures rule following in decentralized setups, despite DeFi’s lack of central control, tipping the scales toward inventiveness while keeping responsibility in check.
Data Analysis
Analysis of data taps into big data piles to pull out useful clues that help crank up efficiency and make things super personal:
- Pattern Discovery: Scouring through all that buying and selling info analytic programs, pick up on what’s hot in how folks wanna pay or if someone’s trying to pull a fast one.
- Process Improvement: Analytics shine a light on dragging stuff (like when it takes ages to get the thumbs up) and cough up smart ways to make everything zip along much better.
- Personalization: Peeking at what peeps buy lets companies whip up deals, nudge them with payment heads-ups, or toss some bonus points that hit the spot for each person.
Biometric Checks
Biometric securities in digital banking lock things down tight with your one-of-a-kind body features, making sign-ins a breeze without any hitches:
- Facial Recognition: Apps such as Apple Pay and Alipay scan faces to confirm who’s using them, ditching passwords for a smoother, safer option.
- Fingerprint Scanning: This tech is all over mobile payments—it’s quick and trusts folks’ unique prints to check who they are.
- Voice Recognition: When you’re on the phone, your voice can prove it’s you giving transactions that add a secure touch and make things a bit easier.
Computer Vision
When it comes to visual info, computer vision is on the job. It makes sure payment stuff is tight and follows the rules.
- Identity Verification: The system checks passports or IDs to ensure it’s you when making a new account or during big-money moves.
- License & Document Scanning: Shops and money exchange platforms use the tech to check documents like driver’s licenses quickly and without mistakes.
- Anomaly Detection in Transactions: By peeking at visual hints (like messed-up receipts), the computer vision tech raises a flag on stuff that doesn’t look normal to take a closer look.
- Automated Compliance Checks: The tech keeps an eye on papers to make sure they’re up to the legal mark, cutting down on the need for people to double-check and the possible mess-ups.
Bonus Read: Financial Regulatory Compliance Software Development For Compliance Checks
Quantum Computing
Even though it’s kinda new, quantum computing is set to cause a revolution in how money matters work with mind-blowing speed in crunching numbers:
- Enhanced Cryptographic Security: Quantum algorithms make way for top-notch security in cryptography. They create secure codes no one can crack, keeping our deals safe from upcoming dangers.
- Faster Transaction Processing: Imagine if transactions were zipped by like lightning! That’s what quantum tech could do dealing with complicated math fast for stuff like instant worldwide payments.
- Future-Proofing Payment Systems: Getting a head start with quantum tech means setting ourselves up to stay in the game. We’ll be ready for when quantum becomes the big boss in the business.
AI-Driven Regular Tech (RegTech)
Mixing AI with rules and regulations? That’s RegTech for ya. It’s all about sticking to the law and being super efficient with our payment networks.
- Real-Time AML (Anti-Money Laundering) Monitoring: AI scans the cash flow immediately, looking for anything weird to stay in line with the Anti-Money Laundering rules on the spot.
Bonus Read: AML Software Development – A Detailed Guide for CEOs
- Automated Tax Compliance: Machines handle the tax by themselves, getting it right and reducing the chance of messing up audits.
- Adaptive Regulatory Updates: As the rules change up, AI just shifts gears to stay on track, so no one’s got to stress over doing it by hand.
Put it all together; these smart tools are a big deal; they make online money moves quick, tight, and more tuned into what folks need while figuring out the crazy rule maze. As this tech keeps improving, it will switch up the game on handling cash online, making it cooler, slicker, and much safer.
AI Use Cases in Payments: 5 Applications of AI in Payments
Use cases of AI in payments change how we deal with transactions in the payments world. It’s making sure things are safe and personalizing how customers experience everything. Here’s an example of the five use cases that have a significant impact, with an example of each.
1. Fraud Detection
AI models learn “normal” behaviours for every customer and flag anything abnormal as it occurs. They don’t have a fixed set of rules; rather they consider a multitude of signals, including transaction speed, device type, and IP location, and they become more refined as they receive fresh data.
PayPal has by far processed billions of transactions and applies AI to see the big picture not the red flags. It can detect real threats and prevent false positives involving legitimate customers by analyzing AI-driven transaction-monitoring velocity, IP addresses, and device fingerprints. The results indicate: PayPal’s fraud rate is 0.32% vs. the average of other merchants at 1.32%.
2. Risk Assessment
AI collects data, such as credit history and transaction patterns, and uses it to create meaningful risk signals, scoring each individual or transaction based on the risk of fraud, default, or disputes. It is an ongoing learning process, so its evaluations remain relevant in changing environments.
On signing up, Stripe’s AI analyzes a company’s website, payment track record, and industry risk to give it a risk score. Additional review is done for higher-risk sellers and quicker approval for lower-risk sellers. Stripe claims it has achieved a 70% improvement in the accuracy rate of transactions that it had previously declined, and a 35% drop in the number of transactions that required retries.
3. Cross-Border Payments
Sending money internationally has always required 3-5 business days and fees/exchange rates of 5-7%. AI’s role is to forecast currency trends, choose the quickest and economically most viable path and then automate compliance assessments of AML, KYC and sanctions.
Wise uses AI to analyse its global network of banking and payment partners and determine the optimal path for every transaction; automating ID verification and sanctions screening, in the process. Not only did more than 150 machine learning systems support them, but Wise handled 1.2 billion transactions over the past year with only 300 people.
4. Know Your Customer (KYC)
KYC helps prevent fraud and money laundering on the part of businesses and consumers by verifying who they are. With OCR capabilities, AI reads information from ID cards, uses facial recognition to compare a selfie with the ID photo (including a liveness check, such as blinking), and cross-references with government and PEP lists.
For new users, Revolut asks its users to upload an ID and take a selfie via the app. The document is read by AI, the face is matched, and the information is compared to global watch lists, only more complex cases being reviewed by humans. The money lost to card fraud in connection with fake investment schemes decreased by 30% for Revolut.
5. IVR Payments
Payment via phone doesn’t have to involve navigating through a maze of menus. AI in payment gateways securely processes payment requests by connecting voice-enabled systems to them, allowing customers to pay bills through natural-language commands and voice recognition. The experience is more like a conversation than a script.
American Express uses AI to help its IVR system so cardholders can make payments by voice. The assistant comprehends the request, has the appropriate follow-up questions – such as: Which card should I use or how much does it cost? and securely carries out the transaction. If it is a personal touch that is required, it passes it on to a human agent. Agentic AI in the payments industry thus enhances the customer experience and minimizes the human touch.
Turn your payment innovation ideas into practical AI solutions built around your business needs.
How to Integrate AI into Your Existing Payment System
AI in payment processing is causing a revolution in how companies manage their money moves. It gives a chance to make things smoother, beef up security, and make customers happier. Slipping AI into what you’ve got for payments might sound scary, but tackle it with a plan, and it’ll switch things up. Okay, let’s break it down into steps to get it done.
Step 1 – Assess Your Current Infrastructure
Start by taking a good look at what’s already in place. Find the scope of embedding AI in payment processing setup as it stands. You wanna know the nuts and bolts so that when AI steps in, it feels right at home. This doesn’t have to be a headache—just a solid check-up.
Kick things off by figuring out your current position. Start by checking out the payment processes you’ve got going—zero in on how you handle business, spot fraud, and manage reconciliations. Look for trouble spots holding you back or hitting your wallet, such as slow deals or fraud rates that are going up. After that, see if your setup is ready to buddy up with AI. Got your APIs in the latest shape? Is your info the kind that AI can jive with? Doing this assessment lays the groundwork.
Step 2 – Define Clear Objectives
AI’s no fairy tale fix; it demands clear orders. Aim for precise outcomes you want to nail. You could be looking to chop down fraud figures by 20% or slash the time deals take right down the middle. Connect those aims to the big picture, like making clients happier or reducing what it costs to run your show. Solid targets ensure the team’s on the same page and make it simple to check how well you did when it’s all said and done.
Step 3 – Choose the Right AI Tools
Every AI tool varies in capability. Pair the tech with your requirements. Machine learning models are top-notch requirements for detecting tricky fraud trends, and natural language processing amps up chatbots to provide better customer help. Mind how well the tool can expand. Is it built to develop along with your business? Also, think about cloud solutions that are quick and easy to implement versus having your setup on-site, which offers more command but costs more at the start. The assistance you get from sellers is super important as well. Choose allies who will stay the course.
Step 4 – Ensure Data Readiness
Make sure your data’s ready for AI because it needs it. You gotta scoop up all that historical payment stuff – we’re talking records of transactions, reports of sketchy things, chats with customers – and give it a good scrub to eliminate any double entries or missing bits. And hey, you can’t ignore privacy rules like GDPR or CCPA, so keep the personal details down and play by the rules. To make your AI super snappy in real-time, get data pipelines going that zap all the new info straight into your algorithms the moment money moves.
Step 5 – Start with a Pilot Project
Ease into it; don’t just dive in headfirst. Start small, like trialing AI to catch fraud in just one type of transaction, for example, those done with credit cards. You should keep an eye on things that tell you how well it’s doing, like how often it flags that it’s okay or how quick it is. This mini-test will help you find problems, fine-tune things, and get confident before you go big.
Step 6 – Integrate with Existing Systems
Time to hook up the AI with your current cash-moving tech. Use AI payment API integrations or go-betweens to connect your cool new tools to the old stuff you have. Try not to shake things up too much—bring it in bit by bit and make sure it can play nice with old tech so you don’t break anything. Testing is super important because messing up here could cost you money or make customers mad.
Step 7 – Train Staff and Monitor Performance
Make sure your crew gets the hang of the AI. Show them the ins and outs, what the AI looks for, and how to step up when it’s called for. Don’t just leave the AI alone—establish observation methods to catch when model drift happens (like when it starts missing the mark because patterns change) and maintain strong performance. It’s key to touch base to confirm it’s living up to expectations.
Step 8 – Scale and Optimize
After the pilot shows its value, it’s time to level up. Apply AI to more areas—consider sorting out how folks can pay or guessing upcoming cash flow. Craft feedback loops for consistent enhancements: as your customers’ habits transform, your algorithms should, too. The work to perfect the system never stops—remain adaptable and persist in polishing your approach.
Putting AI to work in your payment setup is more than just a tech move—it’s a savvy step for your biz. Check out what you’ve got, figure out where you wanna go, and grow with care. Kick things off on the down-low, pick up the pace, and peek at how your payment process gets slicker.
Challenges of AI in the Payments Industry & Their Solutions
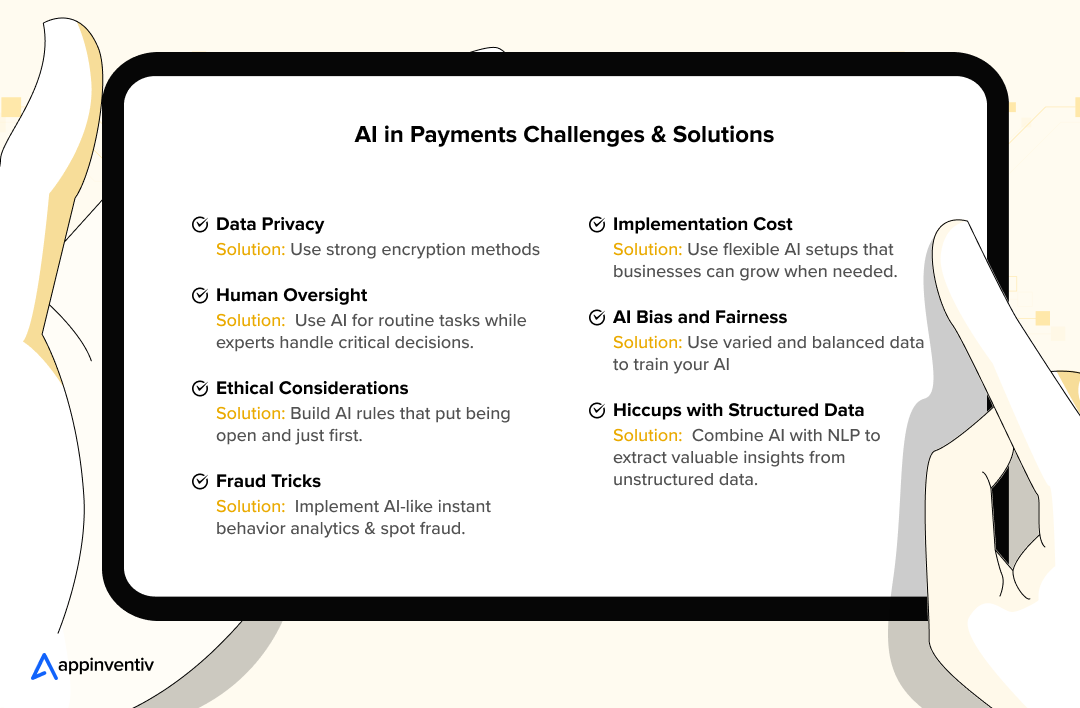
In the payment world, AI is causing a revolution, speeding up transactions, improving the ability to spot fraud, and making the shopping experience super personal. Yet, there are many big problems when you mix AI with money. We’ll dive into these challenges of AI in the payments industry and devise some smart ways to fix them.
Data Privacy
AI must gobble up lots of information about us to do its job right. But folks are kinda worried about who’s grabbing their personal and bank details, where that data’s lounging around, and what people are doing with it. Plus, with all these rules like GDPR and CCPA, if you mess up, it’s gonna cost a ton and make you look bad.
Solution: Use strong encryption methods and make personal data anonymous to keep it safe. Stick to privacy-first ideas, ensuring they fit worldwide data protection rules. Regular checks and clear data methods can also make customers trust you more.
Need for Human Oversight
Even though AI can do some stuff independently, it can sometimes mess up. If we rely too much without people checking on it, we can make mistakes, get things wrong, or cause stuff we didn’t mean to happen in how we pay for things.
Solution: Go for a mixed plan where AI takes care of the easy stuff, but people with know-how keep an eye on the big choices and jump in if weird stuff pops up. Always watching how things are going and giving feedback can improve AI and keep everyone informed about who’s responsible.
Ethical Considerations
AI handling payments needs to deal with tricky moral issues. It’s gotta make sure everyone has the same chance to use financial stuff and not do anything shady. Like, there’s a chance that robots might leave out people who don’t get these services, or they might care more about making money than being fair.
Solution: Build AI rules that put being open and just first. Get people involved when you’re making it, and do ethics checks often. This way, AI will match up with what people think is right and not cause trouble.
Fraud Tricks
While AI is getting better at spotting cheats, the bad guys also use AI for trickier stuff. They’re coming up with things like fake identities or scams using deepfakes. It’s like a constant battle, with security and crooks always trying to one-up each other.
Solution: Implement cutting-edge AI-like instant behavior analytics and spot oddities to get the jump on new threats. Team up with IT security whizzes and exchange know-how industry-wide to get ready to block scam tricks.
Hiccups with Structured Data
Systems for making payments mess with neat data like transaction logs, but AI is all about mixing it up with varied, messy info. Wonky or not, whole data can mess with AI’s game by giving spot-on hints or guesses about what’s coming.
Solution: Roll out data prep moves to tidy up and make the data consistent. Mix AI with cool tools such as NLP to pull out the good stuff from messy sources, such as what customers say or help requests, making the whole system work better.
Implementation Costs
Setting up and keeping AI systems for payments can cost a lot. There are bills for skilled gear people and for keeping the system current. Small companies might have a hard time getting these techs.
Solution: Start with small, flexible AI setups that businesses can grow when needed. Work with other companies or use open-source tech to keep early expenses low while staying on top of the latest innovations.
AI Bias and Fairness
Sometimes, AI systems pick up biases from the data they learn from. This can lead to not-so-fair decisions like who gets a loan approved or who gets flagged for fraud. It’s not cool since it can hit some groups of people harder than others, making folks doubt the system is fair.
Solution: Use varied and balanced data to train your AI and keep checking to make sure it’s not biased by using tests designed to measure fairness. Go for AI that explains its choices so you can spot and fix biases if they pop up.
ROI of AI in Payments
AI pays for itself in three places: what you spend, what you lose, and what you earn.
- Lower costs: Automating reconciliation and invoice matching can remove up to 70% of manual effort, while smart payment routing can trim processing fees by roughly a quarter.
- Fewer losses: Behavior-based fraud models catch real threats without blocking good customers. They can reduce false positives by 15–25%, protecting sales that rigid rules would have turned away.
- More revenue: Higher approval rates, intelligent payment retries, and onboarding that can run up to 70% faster help convert more customers, sooner.
What to watch: Returns don’t arrive all at once. Focused use cases like fraud triage often pay back within 6–12 months, while enterprise-wide rollouts can take 2–4 years, especially with legacy systems. Track AI usage costs closely too, as unchecked spend can quietly erode the gains.
Tip: Start with one high-impact use case, set a baseline, and measure results before scaling.
How Appinventiv is Supporting AI in Payments
We at Appinventiv lead the way in fusing artificial intelligence (AI) into the payments scene. This move is shaking things up, making how companies and people deal with their money moves differently. Our payment software development services perfectly blend AI expertise and digital acumen to help businesses lock things down tight, make their work smoother, and give customers something just for them.
Having a solid history of working with huge brands like KFC, Domino’s, and IKEA, creating payment systems that grow with the market and keep things safe and fresh for the fast-paced online world.
We at Appinventiv take a well-rounded approach to AI in payments, blending cutting-edge tech with a focus on client needs. We first put security, growth potential, and adaptability, creating answers that tackle today’s requirements and prepare businesses for what’s coming.
From protecting transactions to streamlining processes and tailoring experiences, Appinventiv stands as a reliable ally in dealing with the ins and outs of today’s payment scene. Contact us now!
FAQs
Q. How is AI Being Used in Payments?
A. AI in digital payments transforming the payments sector through diverse cutting-edge solutions. It enhances transaction efficiency by detecting patterns and refining processes, delivering quicker and more dependable payment services. AI in digital payments tracks payment activities for potential threats, employing advanced algorithms and user behavior monitoring to combat fraud and minimize financial exposure.
Q. How does artificial intelligence in the payments industry improve security?
A. Artificial intelligence in the payments industry enhances security by deploying advanced algorithms to continuously monitor and analyze transaction data. Machine learning technology in payment processing strengthens protection through sophisticated algorithms that constantly evaluate transaction patterns.
Artificial intelligence in digital payments recognizes irregularities, spots fraudulent behavior, and identifies questionable activities instantly, reducing monetary risks. Capabilities such as biometric verification and user behavior monitoring add extra layers of security against unwanted entry. By dynamically responding to new security challenges, machine learning in payment systems delivers comprehensive safeguards for companies and consumers, building confidence in electronic payments.
Q. How does AI in payment processing reduce transaction costs?
A. AI in payment processing lowers transaction costs by automating repetitive tasks and minimizing errors that lead to financial losses. AI streamlines operations like payment reconciliations, currency conversions, and chargeback management, reducing the need for manual intervention and associated labor costs.
Q. What are some generative AI use cases in payments to improve customer support?
A. Generative AI use cases in payments include enhancing customer support through advanced automation and personalization. For instance, generative AI powers intelligent chatbots to resolve payment-related queries—like transaction disputes or refund requests—in real time by generating human-like responses. It can also create tailored troubleshooting guides or payment instructions based on user input, reducing response times and improving customer satisfaction in payment systems.
Q. How will the future of AI in payments impact transaction speed and scalability?
A. The future of AI in payments promises to revolutionize transaction speed and scalability by leveraging advanced algorithms and real-time data processing. Thanks to predictive analytics and automated optimization, that allows AI in payment systems to handle exponentially higher transaction volumes with minimal latency.

Fast 2-minute response, fully NDA-protected.
AI-Native Security Maturity Model: Score Where Your Security Stack Stands
Key takeaways: If Human oversight scores below 2, you're at Level 3 at most, whatever your total score says. Moving to Level 3 starts with unifying your telemetry, which most teams can do with tools they already own. Define approval points before you automate response. Oversight added later costs more. Buy a platform when your…
The AI ROI Crisis: Why Enterprises Are Struggling to Prove Value and How to Fix It
Key takeaways: AI ROI is a capital-allocation question. Boards want payback periods and P&L impact. AI ROI challenges rarely have a single cause. Data, legacy systems, use-case choice, ownership and stalled pilots compound each other. Choose two or three outcome metrics per use case, set the baseline first, and report in dollars. Make every further…
Retrieval Augmented Generation in Australia: Architecture, Implementation and Cost
Key takeaways: RAG grounds LLM answers in approved content, improving reliability without retraining a model. Data quality and access permissions decide production outcomes more than the model. Indicative build costs run from AUD 70,000 to 700,000, driven by data and integrations. Measure value against a pre-deployment baseline, separating realised benefits from projected savings. A general-purpose…